Your First Home: Could a 2.5% Deposit Help First-Time Buyers Onto the Property Ladder?
Your First Home: Could a 2.5% Deposit Help First-Time Buyers Onto the Property Ladder?
Getting onto the property ladder has become increasingly difficult for many first-time buyers, with one of the biggest hurdles often being the amount of deposit needed.
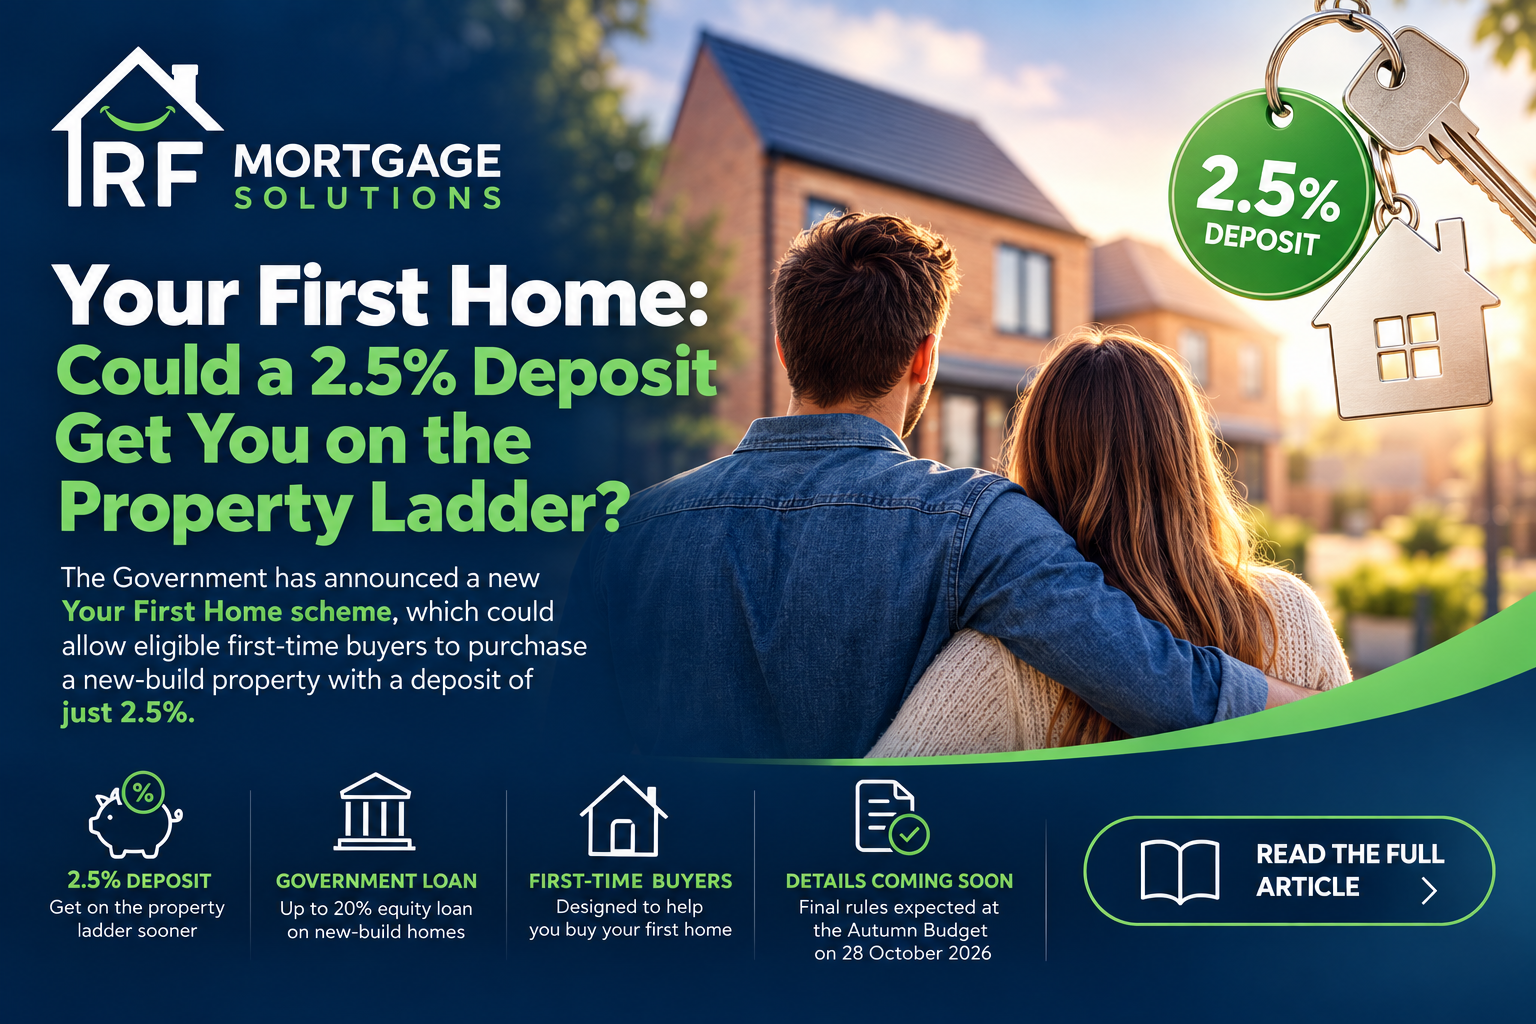
The Government has now announced plans for a new “Your First Home” scheme, which could allow eligible first-time buyers to purchase a new-build property with a deposit of just 2.5%.
At first glance, that sounds extremely attractive. But there is more to the scheme than the headline deposit figure, particularly as it will also involve a Government equity loan of up to 20% of the property's value.
So, how could the scheme work, how does it compare with the old Help to Buy scheme, and what should first-time buyers be aware of?
How could the new Your First Home scheme work?
Under the proposals announced so far, eligible first-time buyers in England could purchase a new-build property using:
- A minimum 2.5% personal deposit
- A Government equity loan of up to 20%
- A mortgage for the remaining amount
If the full 20% equity loan were used, the mortgage required could therefore be approximately 77.5% of the purchase price.
For example, on a property costing £250,000:
- 2.5% deposit = £6,250
- 20% Government equity loan = £50,000
- Mortgage required = £193,750
For somebody struggling to build a traditional 5% or 10% deposit, reducing the initial deposit requirement to £6,250 could potentially make buying a first home achievable sooner.
However, the Government contribution is not a grant. It is an equity loan, and that distinction is extremely important.
Is the scheme limited to properties costing £100,000?
Some of the initial discussion around the scheme has referred to a £2,500 deposit on a £100,000 property.
This can understandably create the impression that £100,000 is the maximum property value under the scheme.
However, based on the information announced so far, £100,000 is not the proposed maximum purchase price. It is simply an easy example demonstrating that a 2.5% deposit on a £100,000 property would be £2,500.
The Government has said that property price caps will apply, together with household income limits, but the exact figures have not yet been confirmed. These details will be particularly important in areas where property prices are considerably higher than £100,000.
Is this the return of Help to Buy?
There are certainly some similarities.
Under the previous Help to Buy Equity Loan scheme, buyers generally provided a minimum 5% deposit, with the Government providing an equity loan of up to 20% outside London and a mortgage making up the remainder.
The proposed Your First Home scheme could broadly look like this:
Previous Help to Buy
5% buyer deposit
20% Government equity loan
75% mortgage
Proposed Your First Home
2.5% buyer deposit
Up to 20% Government equity loan
Approximately 77.5% mortgage
The most obvious difference is therefore the reduction in the minimum deposit.
For first-time buyers who have sufficient income to afford the mortgage but are struggling to save a larger deposit, this could potentially make a significant difference.
But what exactly is an equity loan?
This is perhaps the most important part of the scheme for buyers to understand.
If the Government provides a 20% equity loan, it effectively has an interest in 20% of the property's value, rather than simply lending a fixed amount of money in the same way as a traditional loan.
For example, suppose you purchase a property for £250,000 and receive a 20% equity loan of £50,000.
If the property subsequently increases in value to £300,000, a 20% share would then be worth £60,000.
Equally, if the value of the property fell, the amount represented by that 20% share could also reduce, subject to the final rules of the scheme.
This is why buyers shouldn't look at the 2.5% deposit in isolation. The overall arrangement — mortgage, equity loan and future repayment — needs to be considered together.
What happens to the equity loan afterwards?
This is one of the major details we are still waiting to discover.
The Government has confirmed that the equity loan is expected to have an initial interest-free period, but the full terms have yet to be announced.
We still need confirmation of matters including:
- How long the interest-free period will last
- What interest or charges will apply afterwards
- How and when the equity loan can be repaid
- Whether buyers can repay the equity loan in stages
- How the property will be valued when repayment takes place
- The applicable household income limits
- Regional property price caps
- Which lenders will participate
- The precise eligibility requirements
These details will ultimately determine how attractive the scheme is for individual buyers.
Could it help first-time buyers?
Potentially, yes. But, one of the frustrations I regularly see as a mortgage adviser is first-time buyers who have sufficient income to support a mortgage but are held back by the time it takes to build their deposit.
Reducing the minimum deposit from 5% to 2.5% could shorten that journey considerably.
However, a smaller deposit doesn't automatically mean that buying a property is affordable.
Buyers will still need to satisfy a mortgage lender's affordability and credit assessment and should also budget for the other costs involved with purchasing a property, such as legal fees, surveys and moving expenses.
There is also the longer-term consideration of eventually repaying the Government's equity share.
Should you wait for the scheme before buying?
Not necessarily. However, this is where individual circumstances become particularly important.
If you're already in a position to buy with a conventional mortgage, delaying a purchase purely to access the new scheme may not necessarily be beneficial.
Likewise, a 5% or 10% deposit mortgage without an equity loan may be more appropriate for some buyers because they retain full ownership of any future increase in the value of their home.
For others, however, the proposed scheme could provide the missing piece that allows them to buy considerably sooner.
The important thing is to compare the options rather than assuming that the mortgage requiring the smallest deposit will automatically be the most suitable.
What happens next?
The full details of the Your First Home scheme are expected to be confirmed as part of the Autumn Budget on 28 October 2026.
Until then, some important questions remain unanswered, particularly around property price caps, income limits and the future cost and repayment of the Government equity loan.
Once those details are available, we will have a much clearer picture of who is likely to benefit.
Thinking about buying your first home?
Whether you're ready to buy now or you're still building your deposit, understanding how much you could potentially borrow is a useful place to start.
At RF Mortgage Solutions, I can look at your income, deposit and circumstances to establish the mortgage options currently available to you — and, once the full details are confirmed, whether the new Your First Home scheme could provide another route onto the property ladder.
You don't necessarily need to wait until you've saved a 10% deposit before having the conversation.
Sometimes understanding your options today can help you build a much clearer plan for buying your first home tomorrow.
Get in touch today for a friendly, no-obligation conversation about your options. RF Mortgage Solutions - Mortgage advice tailored to you.
📞
01233 516067
✉️
info@rfmortgagesolutions.co.uk
Your home may be repossessed if you do not keep up repayments on your mortgage.