Government Mortgage Schemes Explained – Help for Buyers
Government Mortgage Schemes Explained – Help for Buyers
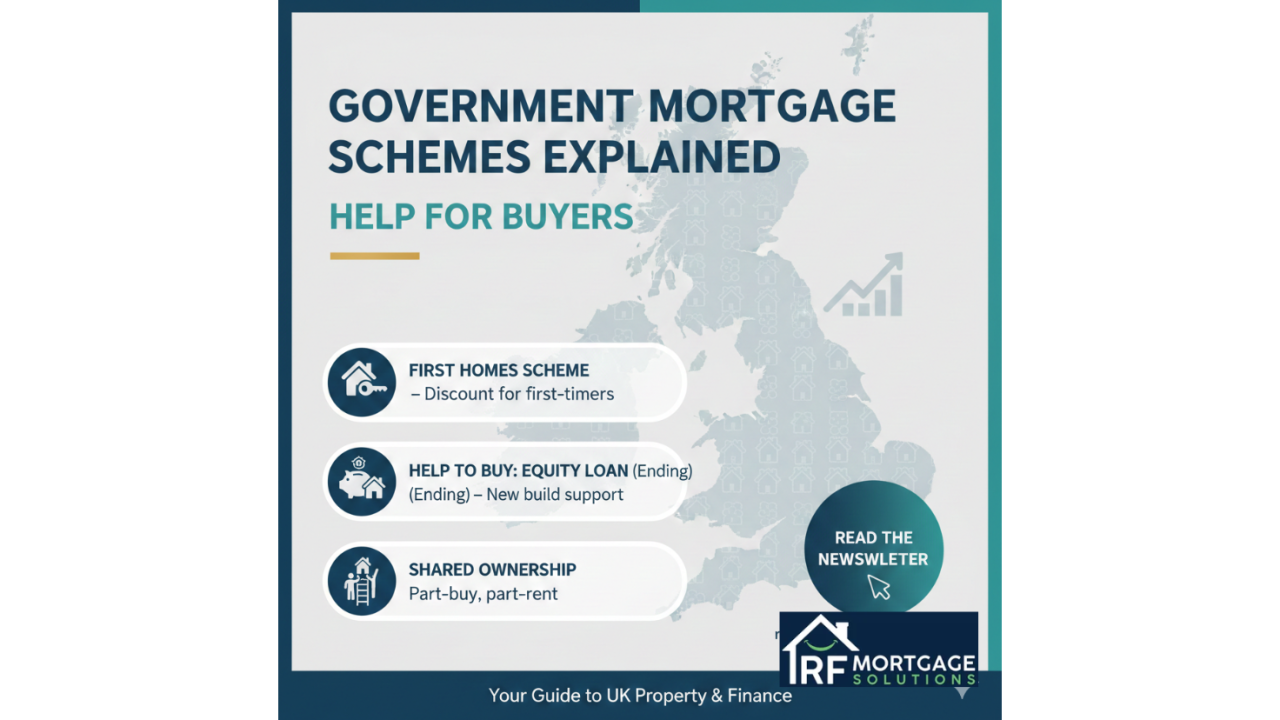
At RF Mortgage Solutions, we often meet buyers in Kent and beyond who say: “If only there was a scheme that lowered the deposit or made mortgages more accessible.” The good news: across the UK, the government still maintains a number of mortgage-support and home-ownership schemes designed to help people onto the housing ladder. Below is a breakdown of what’s available in late 2025 — and what buyers in Kent should know.
📌 What’s on Offer in 2025
Mortgage Guarantee Scheme (since July 2025)
- In July 2025 the government made the Mortgage Guarantee Scheme permanent. Under this arrangement, lenders offering 91–95 % loan-to-value (LTV) mortgages are backed by a government guarantee. This incentivises them to provide high-LTV mortgages — meaning borrowers only need a 5% deposit. GOV.UK+2HomeOwners Alliance+2
- Eligible buyers: first-time buyers and home-movers across the UK, provided the property is their main residence and purchase price is within scheme limits (properties up to £600,000 have been referenced). GOV.UK+2HomeOwners Alliance+2
- Why it matters: For buyers in Kent (or anywhere in England), this means it’s still possible to aim for homeownership without needing a 20–30% deposit — a major barrier for many.
First Homes Scheme
- Aimed at first-time buyers (and in many cases “local buyers” or “key workers”), First Homes offers new-build homes at a 30–50% discount off market price. Money.co.uk+2Mortgage One+2
- After discount, buyers need to secure a mortgage for at least half the purchase price and pay a deposit (often as low as 5%). Money.co.uk+1
- This scheme is particularly valuable if you want to live near where you work — which, for many Kent buyers, could mean easy commutes to London or the South East.
Lifetime ISA (“LISA”) (Savings Route)
- The Lifetime ISA remains an option for younger homebuyers saving for a deposit. You can save up to £4,000 per tax-year, and the government adds a 25% bonus. experian.co.uk+1
- You need to hold the LISA for at least 12 months before using it to buy, and the property value typically must stay below a certain threshold (commonly £450,000). experian.co.uk+1
- LISA can pair well with a 95% mortgage under the Guarantee Scheme — making the path to home ownership smoother.
Other Schemes & Notes
- Some historic schemes like the old “Help to Buy: Equity Loan” (where government loaned 20%–40% on new-build homes) are no longer open to new applicants in England. GOV.UK+2HomeOwners Alliance+2
- Buyers looking to build their own home instead of buying a pre-built home may explore options such as a “self-build mortgage + government-backed support,” though availability and terms vary. Mortgage One+1
💡 What This Means for Kent-Based Buyers (Your Clients)
- Lower deposit barriers — With the Mortgage Guarantee Scheme, a 5% deposit + 95% mortgage is realistic, which can open doors for many first-time buyers struggling to save hefty deposits.
- Discounted new-builds available — If you’re advising homebuyers in Kent, the First Homes Scheme could provide access to discounted properties, potentially within commute distance to London or South-East hubs.
- Savings + Mortgage combo works — For younger buyers (e.g. under 40), a LISA for a deposit + a 95% mortgage could be an efficient strategy.
- Act soon, check eligibility — As with all government-backed housing schemes, there are eligibility criteria, price caps, and regional/local restrictions (especially for First Homes).
📝 How RF Mortgage Solutions Can Help
At RF Mortgage Solutions, we specialise in guiding clients through these schemes:
- Assessing eligibility for First Homes or high-LTV mortgages under the Mortgage Guarantee Scheme
- Structuring deposit savings (like LISA) and mortgage financing in a tax-efficient, sustainable way
- Advising on affordability, market conditions in Kent & South East, and long-term property strategy
RF Mortgage Solutions will help you navigate the paperwork and get the best possible mortgage outcome under current UK government support schemes.